




If you keep a debits and credits cheat sheet within reach while you work, you are in good company. Recording a debit as a credit, or a credit as a debit, is one of the most common bookkeeping mistakes, and it usually goes unnoticed until it is three months and forty entries deep.
A printable cheat sheet for accounting debits and credits that sits on your desk, or that you can hand to an employee, takes the guesswork out of every entry. We built one for you below.
In GlassJar, you enter each transaction on a single screen and the software posts both sides of the entry for you. Our accounting software for small business posts the correct debit and credit to the correct accounts for every transaction you categorize, which lowers the chance of posting to the wrong side. Learn more today!
Key Takeaways
- Debits increase asset and expense accounts, while credits increase liability, equity, and revenue accounts.
- Every transaction posts equal debits and credits across at least two accounts, so a trial balance that does not net to zero reveals an error.
- Your bank calls a deposit a credit because it is a liability on their books, while the same deposit is a debit to your cash asset.
- Buying a laptop with cash debits the equipment account and credits the cash account, and taking a bank loan credits loan payable.
- GlassJar posts the correct debit and credit for every transaction you categorize, which removes the manual error risk the cheat sheet guards against.
The One Page Cheat Sheet
Every rule that is needed to post an entry correctly is contained in the two tables below, and the tables are intended to be printed and kept at the desk where entries are recorded. The explanations further down the page set out the reasoning behind each rule for readers who want the mechanism behind the table as well as the table itself.
| Account type | Normal balance | Increased by | Decreased by | Where it reports |
|---|---|---|---|---|
| Asset | Debit | Debit | Credit | Balance sheet |
| Liability | Credit | Credit | Debit | Balance sheet |
| Equity | Credit | Credit | Debit | Balance sheet |
| Revenue | Credit | Credit | Debit | Income statement |
| Expense | Debit | Debit | Credit | Income statement |
Debits increase asset accounts and expense accounts, while credits increase liability accounts, equity accounts and revenue accounts, and the total of the debits in every entry is equal to the total of the credits in that same entry.
Download the one page cheat sheet as a PDF. It is a single US Letter page, it is free, and there is no sign up required.
The last column of the table shows the financial statement on which each account type is reported. Asset accounts, liability accounts and equity accounts are reported on the balance sheet, and the layout of a balance sheet can be seen in the free balance sheet template. Revenue accounts and expense accounts are reported on the income statement, and an income statement can be built in a few minutes with the free profit and loss statement generator. The balance sheet template and the profit and loss statement generator are both free to use, and neither tool requires an account to be created.
Three worked journal entries
The three transactions below are among the transactions that most small businesses record when the books are first set up, and each of the three transactions is worked through again in more detail further down the page.
Entry 1 records a cash payment of $500 for office supplies that are used up during the current month.
| Account | Debit | Credit |
|---|---|---|
| Office supplies expense | 500.00 | |
| Cash | 500.00 |
The office supplies expense account is increased on the debit side of the entry, and the cash account, which is an asset account, is decreased on the credit side of the entry.
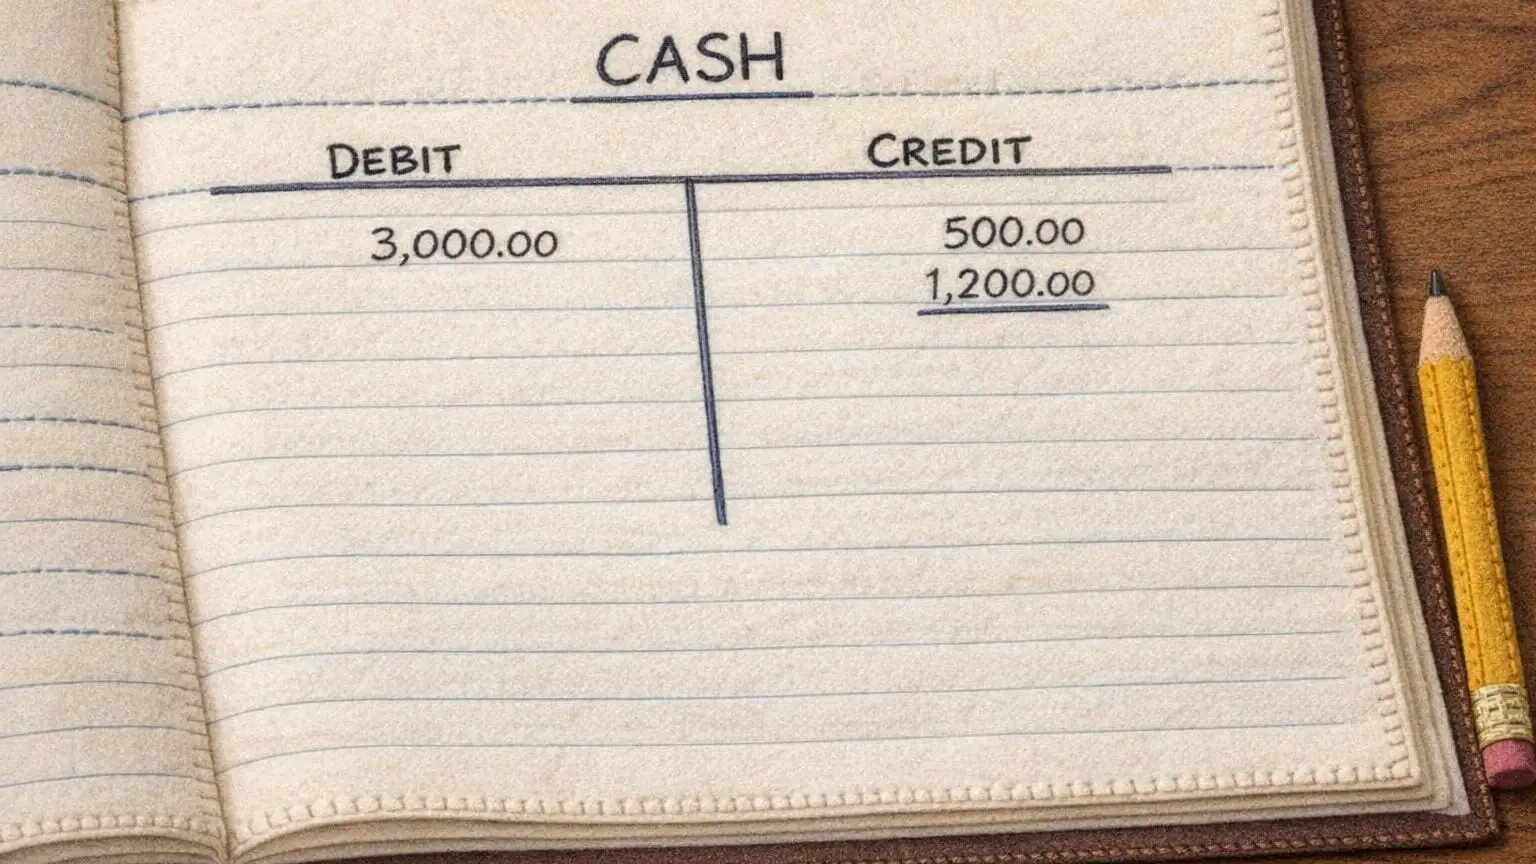
Entry 2 records the collection of $3,000 from a customer who is paying an invoice that was issued in an earlier period.
| Account | Debit | Credit |
|---|---|---|
| Cash | 3,000.00 | |
| Accounts receivable | 3,000.00 |
The cash account, which is an asset account, is increased on the debit side of the entry, and the accounts receivable account, which is also an asset account, is decreased on the credit side of the entry. The revenue for the sale was recorded at the time the invoice was issued, so the revenue account is not affected again when the customer payment is collected.
Entry 3 records a loan payment of $1,200, of which $1,000 is applied to the loan principal and $200 is applied to the interest on the loan.
| Account | Debit | Credit |
|---|---|---|
| Loan payable | 1,000.00 | |
| Interest expense | 200.00 | |
| Cash | 1,200.00 |
The loan payable account, which is a liability account, is decreased on the debit side, the interest expense account is increased on the debit side, and the cash account is decreased on the credit side of the entry. The two debits in Entry 3 total $1,200, and the debit total of $1,200 matches the single credit of $1,200 that is posted to the cash account.
What Are Debits and Credits?
Debits and credits are the two halves of every accounting entry. A debit is entered on the left side of an account and a credit is entered on the right side of an account. The difficulty for most people is that a debit does not always mean an increase and a credit does not always mean a decrease. Whether the account goes up or down depends on the type of account that is being used.
A debit increases the balance of an asset account and a debit increases the balance of an expense account. A credit decreases the balance of an asset account and a credit decreases the balance of an expense account. The reverse is true of liability accounts, equity accounts and revenue accounts. Those three types of accounts are increased by a credit and decreased by a debit.
The everyday use of the words adds to the confusion. When a bank tells a customer that the customer’s checking account has been debited, the balance of that account has gone down. When a debit is posted to the cash account in a business ledger, the balance of that account goes up. The reason for the difference is that the bank and the business are recording the same transaction from opposite positions. A deposit of $5,000 is recorded by the bank as a credit, because the deposit is a liability that the bank owes to the customer. The same deposit is recorded by the business as a debit, because the $5,000 is an asset that the business now owns.
For this reason, a debit should not be understood as money leaving the business and a credit should not be understood as money arriving. The relationship is rarely that direct.
Understanding the Double-Entry Bookkeeping Method
The system that produces this result is called double-entry bookkeeping, and double-entry bookkeeping has been in use since at least the fifteenth century. Every transaction is recorded as a debit in one account and a credit in another account, and when one half of a transaction is omitted, the total of the debits will no longer equal the total of the credits.
The report that identifies an unbalanced set of books is the trial balance. A trial balance lists every account together with the debit total or the credit total that is held in that account, and the debit total and the credit total on the trial balance are expected to agree. In practice the debit total and the credit total frequently do not agree, particularly in the books of a small business.
The error that caused the difference between the debit total and the credit total still has to be located and corrected, but the trial balance makes the business aware of the error while the books are being kept, rather than during tax season or during the sale of the business, when a potential buyer begins to examine the books in detail.
Accounting Debits and Credits Cheat Sheet
There are five main account types to which debits and credits are assigned when an entry is recorded. The One Page Cheat Sheet near the top of this article summarizes how each of the five account types behaves, and an example entry for each account type is given below for readers who find that the table alone does not make the rules clear.
Assets
An asset is anything the business owns, including cash, equipment, inventory and accounts receivable. The balance of an asset account is increased by a debit and decreased by a credit. When a laptop is purchased with cash for a new employee, the equipment account is debited and the cash account is credited.
Liabilities
A liability is an amount the business owes to another party, and loans, accounts payable and credit card balances are all treated as liabilities. The balance of a liability account is increased by a credit and decreased by a debit. When a bank loan is taken out, the loan payable account is credited and the cash account is debited, and as the loan is repaid the loan payable account is debited and the cash account is credited.
Equity
Equity is the amount that remains for the owner after liabilities have been subtracted from assets. The balance of an equity account is increased by a credit and decreased by a debit. An investment of $10,000 by the owner is credited to the equity account, and a withdrawal of $2,000 taken as an owner draw is debited to the equity account.
Revenue
Revenue is the income that arises from the normal operations of the business. The balance of a revenue account is increased by a credit and decreased by a debit. When a client pays for services or a sale is made, the revenue account is credited and the cash account or the accounts receivable account is debited.
Revenue accounts normally hold credit balances, and revenue accounts are closed out to zero at the end of each accounting period rather than carried forward into the next accounting period.
Expenses
Expenses are the operating costs of the business, such as rent, payroll, supplies and utilities. The balance of an expense account is increased by a debit and decreased by a credit. The rent expense account is debited each month as the cash account is credited. Expense accounts are closed out at the end of the period in the same manner as revenue accounts.
Normal Balances Explained
Each type of account has a side on which the balance of the account is normally held. This side is referred to as the normal balance of the account, and the normal balance is shown in the column labeled “Normal Balance” on the printable debits and credits cheat sheet.
Asset accounts and expense accounts normally hold debit balances. Liability accounts, equity accounts and revenue accounts normally hold credit balances. An account that is holding a balance on the side opposite its normal balance should be examined, because in most cases an entry has been posted to that account incorrectly.
A cash account holding a credit balance is one example of a balance on the wrong side. Cash is an asset, so a credit balance in the cash account would indicate that more money had left the account than had ever entered the account, which only happens when the account is overdrawn, and in most other cases the credit balance means that an entry has been recorded in error.
A revenue account holding a debit balance is a weaker indication of an error than a cash account holding a credit balance. A debit balance in a revenue account can be legitimate in a period with an unusual volume of refunds, although more commonly the debit balance means that a credit has been posted to the wrong account.
For this reason the trial balance should be reviewed for accounts sitting on the wrong side before individual transactions are examined. The review of the trial balance takes only a few seconds, and the review prevents errors from accumulating across multiple accounting periods.
Debits and Credits in Accounting: Cheat Sheet Example
A few common transactions are shown below so that the way debits and credits work in practice can be seen in a complete journal entry rather than in the account rules alone.
Purchasing office supplies for $500 cash
Debit: Office Supplies (expense) $500
Credit: Cash (asset) $500
The office supplies expense account is increased and the cash account is decreased, and both sides of the entry equal $500.
A client pays a $3,000 invoice
Debit: Cash (asset) $3,000
Credit: Accounts Receivable (asset) $3,000
The cash account is increased and the accounts receivable account is decreased, and the revenue for the sale was already recorded at the time the invoice was issued.
Making a $1,200 loan payment ($1,000 principal + $200 interest)
Debit: Loan Payable (liability) $1,000
Debit: Interest Expense (expense) $200
Credit: Cash (asset) $1,200
The principal is removed from the loan payable account, the interest is recognized as interest expense, and the cash account is reduced by the full amount of the payment. This entry is frequently recorded incorrectly, because the full $1,200 is applied to the loan payable account and the interest expense for the year is understated as a result.
The Key Takeaway
Every journal entry balances when the accounts involved in the transaction are identified before anything is posted, the type of each account is then determined, and the amount is recorded on the side that the rule for that account type requires.
Common Debits and Credits, at a Glance
The majority of entries recorded in a small business are drawn from a small set of repeating transactions. The memory device most bookkeepers are taught is DEALER, in which Draws, Expenses and Assets are increased by a debit, while Liabilities, Equity and Revenue are increased by a credit. In each case the account is named before the type of the account is determined, and the rule for that account type is applied once the type of the account is known.
| When this happens | Debit | Credit |
|---|---|---|
| You make a sale on credit | Accounts Receivable | Revenue |
| The customer pays that invoice | Cash | Accounts Receivable |
| A bill arrives, unpaid for now | The expense account | Accounts Payable |
| You pay that bill | Accounts Payable | Cash |
| You buy equipment with cash | Equipment (asset) | Cash |
| You take out a loan | Cash | Loan Payable |
| The owner puts money in | Cash | Owner Capital (equity) |
| The owner takes money out | Owner Draws | Cash |
| You record monthly depreciation | Depreciation Expense | Accumulated Depreciation |
How to Check Your Work
When a set of books does not balance, the cause is usually one of a small number of recurring errors. Each of these errors has a signature that can be recognized before individual entries are examined.
| If you see this | It usually means |
|---|---|
| Your trial balance is not zero | One side of an entry is missing, or the amount was keyed differently on each side. |
| An asset account has a credit balance | Often correct for contra accounts such as accumulated depreciation. Otherwise, check the entry. |
| A revenue account has a debit balance | Usually a refund, a returned sale, or a credit posted to the wrong account. |
| The difference divides evenly by nine | A classic sign of transposed digits, for example 540 entered as 450. |
How a General Ledger Helps Small Businesses
Every debit and credit that has been recorded is held in the general ledger, where the entries are organized by account. Accounts receivable and accounts payable are maintained in sub-ledgers that feed into the general ledger, and the income statement, the balance sheet and the cash flow statement are all produced from the general ledger.
The general ledger is the system of record for the business. This is the case whether the books are maintained by the owner or by a junior employee, because every entry described on this credits and debits cheat sheet is eventually posted to the general ledger. A general ledger that is maintained accurately produces financial statements that are accurate.
GlassJar handles the ledger for you. You categorize a transaction and the correct debit and credit post to the proper accounts, so you never have to write a journal entry yourself. That takes the stress out of bookkeeping and helps prevent one of the most common errors.
If you’re looking for a Zoho alternative or Xero alternative, we’re excited to show you what GlassJar can do for your business. Learn more today!
Bottom Line on Debits and Credits
Debits and credits come down to five rules, one for each account type. Print the debits and credits cheat sheet, keep it somewhere you’ll see it while you work, and the patterns will stick faster than you expect.
If you’re tired of the common complaints about QuickBooks or you just don’t want to work out debits and credits yourself anymore, GlassJar can help. Start your 14-day free trial today!
If you want the rest of the recording layer in the same plain terms, our bookkeeping basics hub collects the reconciliation, chart of accounts and month end guides that build on these rules.
Frequently asked questions
What is the easiest way to remember debits and credits?
The printable debits and credits cheat sheet above sets out the rule for every account type, so the side of each entry can be checked against the table rather than guessed. A GlassJar account removes the need to remember the rules at all, because GlassJar posts the debit and the credit for each transaction that is categorized in the software.
Can you provide a cheat sheet for debits and credits?
A cheat sheet is provided above on this page, and the cheat sheet covers all five account types (assets, liabilities, equity, revenue and expenses). Each row of the cheat sheet shows whether a debit or a credit increases or decreases the account, along with the normal balance that the account carries.
How do I determine between debits and credits?
The account type should be determined first, because asset accounts and expense accounts are increased by debits, while liability accounts, equity accounts and revenue accounts are increased by credits. GlassJar can also be used to remove the uncertainty from small business bookkeeping, because GlassJar assigns the debit and the credit for each categorized transaction.
Do debits always mean money coming in?
A debit does not always mean money coming in, because a debit increases asset accounts and expense accounts and decreases liability accounts, equity accounts and revenue accounts. Whether a debit represents money coming in depends entirely on the account that is debited, so a debit to the cash account represents money coming in, while a debit to an expense account represents money that has been spent.
Why must debits equal credits in every entry?
Debits must equal credits because every transaction has two sides, in which something is received by the business and something is given up by the business, and the recording of both sides is what keeps the balance sheet in balance. An entry that does not balance has recorded only half of the transaction that took place.
Can one journal entry have more than two lines?
One journal entry can have more than two lines, and most real journal entries do have more than two lines. A payroll entry, or a loan payment that is split between interest and principal, has three or more lines, and the only rule for such an entry is that the total of the debits equals the total of the credits.
Which accounts go on the balance sheet and which on the income statement?
Asset accounts, liability accounts and equity accounts are reported on the balance sheet, which shows the position of the business at a point in time. Revenue accounts and expense accounts are reported on the income statement, which shows the performance of the business over a period of time. The table near the top of this page shows the statement for each account type in the last column of the table.